Investor FAQ – Should I pay cash or finance?
The right answer depends on your time horizon, goals, city where you invest, and risk tolerance.
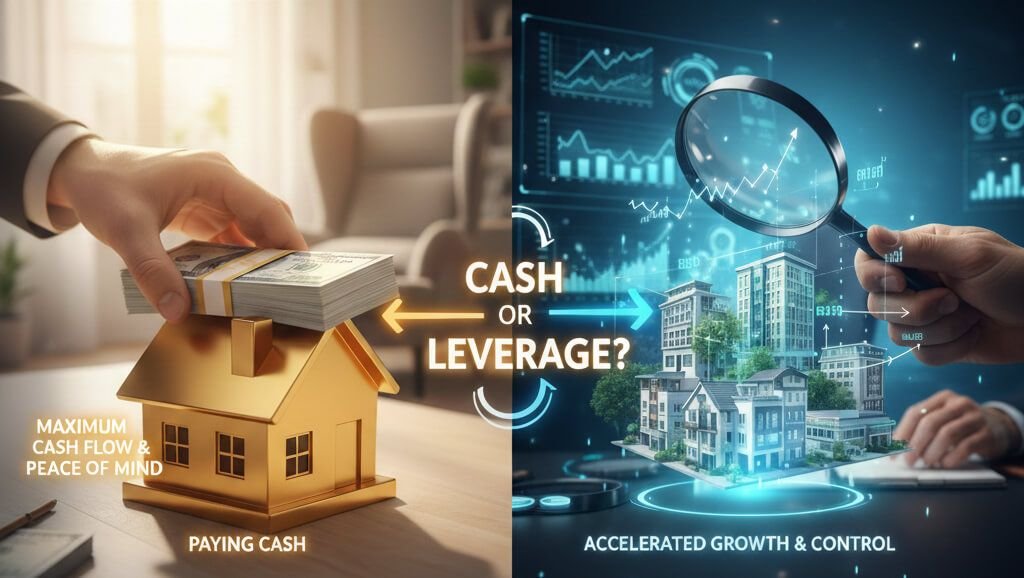
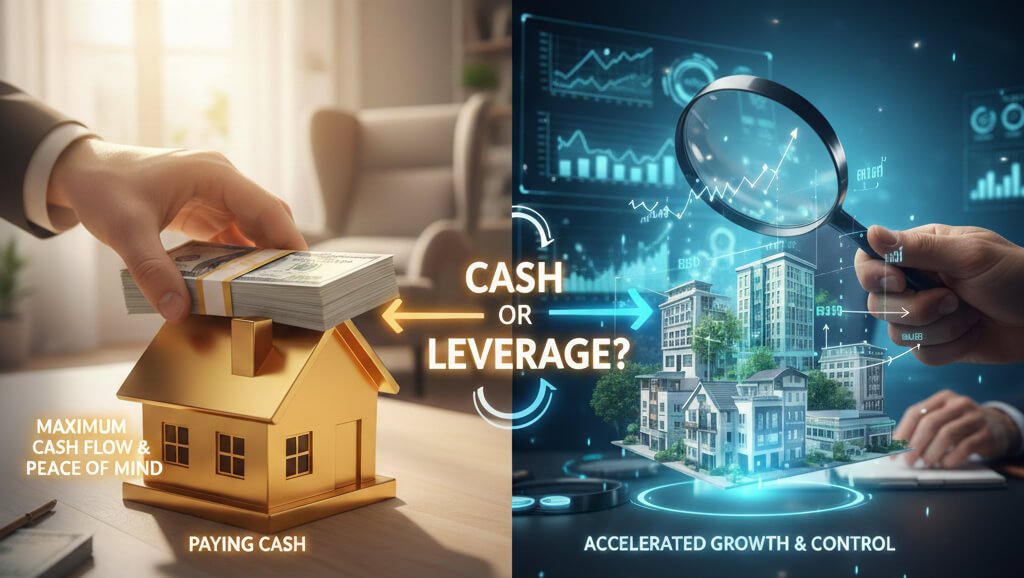
[Created with Gemini]
Now that we have completed all that data crunching and reporting at the beginning of the year, I want to get back to the frequent questions I receive from investors.
Should I Pay Cash or Use Leverage When Buying a Rental?
This is a common question. Using cash can maximize cash flow, and leveraging can maximize ROI. The right answer depends on your investment time horizon, goals, city where you invest, and risk tolerance.
Your Time Horizon Matters
How soon do you need the rental income?
- If you don’t need income for many years, financing usually makes sense. Leverage lets you:
- Control more assets with less cash
- Benefit from appreciation and rent growth
- Use “good debt”—fixed-rate debt tied to income-producing assets
- If you need income soon, paying cash may be better since it maximizes monthly cash flow.
How Leverage Accelerates Growth
Financing allows appreciation to help fund future purchases.
Example assumptions:
- Purchase price: $400,000
- Down payment: $100,000 (25%)
- Mortgage: $300,000
- Appreciation: 8% annually (see our actual 10-year CAGR for our target segment)
- Cash-out refinance at 75% loan-to-value
After about four years, appreciation alone can generate enough equity to fund the down payment on a second property. At that point, you own two appreciating assets instead of one—and the process speeds up as your portfolio grows. (If you want to see more detailed math, go here.)
This is a simplified example. Real-world results depend on transaction costs, inflation, appreciation, and financing terms.
Risk Tolerance
There’s also an emotional factor. Some investors simply sleep better with no debt. If peace of mind is your priority, paying cash is a valid choice.
If you have a higher risk tolerance and want to prioritize long-term appreciation and rent growth, financing should better align with your goals.
Liquidity Considerations
Paying cash for a $300,000–$400,000 property locks up capital in a single asset. If you need access to that money, selling takes time. Financing preserves liquidity and keeps capital available for other opportunities.
Tax Considerations
If you have other passive income, you may be able to offset some of that income using the interest payment deduction and depreciation of a financed rental property. (Make sure to check with your CPA before taking any actions!)
How Knowledgeable Investors Scale
Most investors move through three phases:
- Foundation: Choose a city where prices and rents consistently beat inflation. Work with an experienced team.
- Growth: Use leverage and refinancing until rental income replaces your salary.
- Optimization: Reduce leverage and maximize cash flow once income goals are met.
Most people cannot replace their income using savings alone. Leverage—used correctly in the right market—is what makes scale possible.
Bottom Line
There is no universally “right” answer.
- Cash maximizes short-term income and peace of mind
- Leverage maximizes long-term growth and capital efficiency
The best choice is the one that gets you to your long-term goal fastest and with the least amount of capital at risk.
Related insights
How Will You Finance Your First Rental Property?
7 min read Continuing our new to real estate investing series, this week I will discuss the financing options available to first-time investors. Several…
New to Real Estate Investing Series — Single-Family or Multifamily?
We’re back this week with our new-to-real-estate-investing series. In the first article in this series, we discussed the first step a new investor needs…
New to Real Estate Investing Series – Where Should I Start?
Most of our clients started with no real estate investing experience and a similar goal: “I want to learn how to build long-term wealth…
Thinking about a Las Vegas rental?
A 30-minute conversation about your goals: whether Las Vegas fits your strategy, what a first property costs, and what the process looks like.
- We learn your goals and make sure we’re the right fit
- You get a clear picture of cash requirements and realistic returns
- You leave with next steps, whether or not you work with us