How Will You Finance Your First Rental Property?

7 min read
Continuing our new to real estate investing series, this week I will discuss the financing options available to first-time investors.
Several options are available, and the right one depends on factors such as your credit score, debt-to-income ratio (DTI), available down payment, cash reserves, investment strategy, and whether you plan to occupy the property. Here are some common financing options to consider.
FHA Financing
An FHA loan can be an attractive option if you initially occupy the property as your primary residence. FHA financing is available for properties with one to four units, provided you meet the occupancy and other program requirements. The minimum down payment may be as low as 3.5%, but you must also consider mortgage insurance, property standards, loan limits, and closing costs, which may be higher than those for conventional financing.
For a first-time investor, purchasing a duplex, triplex, or four-plex and living in one unit—often called “house hacking”—can provide an accessible way to begin investing while collecting rent from the other units. However, in Las Vegas, many multifamily properties may not meet your investment criteria.
Conventional Financing
If you will not occupy the property, a conventional investment-property loan may be a good choice. Down-payment requirements vary by property type, loan program, and borrower profile. A qualified buyer may be able to put down as little as 15% [Source]. A larger down payment may help you obtain a lower rate and improve the property’s monthly cash flow.
Credit score, DTI, income documentation, and cash reserves are important qualification factors. Some conventional programs also restrict the number of financed residential properties a borrower may own. Under certain Fannie Mae guidelines, the limit may be as many as 10 financed properties, including the borrower’s primary residence.
DSCR Loans
A debt-service coverage ratio loan focuses primarily on the property’s ability to generate enough income to cover its debt payments. Unlike a conventional mortgage, personal employment income may not be the primary qualification factor. So DSCR loans are simpler to apply for and qualify for. And there are usually no limits on how many DSCR loans you can obtain. However, lenders may still review your credit history, experience, reserves, and down payment.
A common formula for calculating a commercial property’s debt-service coverage ratio is:
- DSCR = (Gross Rent – Taxes – Insurance – HOA – Management) / DSCR Loan Payment
Simplifying:
- DSCR = Net Operating Income / (Annual debt service)
For example, if a property generates $125,000 in annual net operating income and requires $100,000 in annual debt payments, its DSCR is 1.25:
$125,000 ÷ $100,000 = 1.25
A DSCR of 1.25 means the property generates $1.25 in net operating income for every $1.00 of debt service, providing a 25% cushion above the required loan payments.
If a lender requires a minimum DSCR of 1.10 and the annual debt service is $100,000, the property must generate at least $110,000 in qualifying annual net operating income:
1.10 × $100,000 = $110,000
If the property’s qualifying income falls below that amount, the borrower may need a smaller loan, a lower interest rate, a larger down payment, or stronger income before the property can qualify.
Individual DSCR lenders may calculate the ratio differently—often by comparing qualifying monthly rent (obtained via an appraisal) with the full housing payment—so ask how each lender defines income and expenses.
Notes: Recently (fall 2026), we’ve found that DSCR loans often offer lower rates than conventional loans for the same down payment and borrower profile, at least from the lenders that our clients often work with. Though the best DSCR rates usually carry a 3-year or 5-year prepayment penalty.
Portfolio Loans
Banks and credit unions sometimes keep these loans in their own portfolios instead of selling them to outside investors. This can allow more flexible underwriting for borrowers or properties that do not fit standard conventional guidelines. Rates, down payments, and repayment terms may be less favorable, so compare the total cost carefully.
HELOC Financing
Some investors use a home equity line of credit on their personal residence to cover a down payment, renovation costs, or even an entire purchase. The easy access to cash can be useful, but the risk is real. Your home secures the loan, so a deal that goes bad could put your residence in jeopardy. Most HELOCs also have variable rates, which means the payment can rise even if you do not borrow more. Payments may jump again when the draw period ends and repayment begins. A lender may also freeze or reduce the available credit if your finances change or your home’s value drops significantly. Before using a HELOC, make sure the investment can carry the added debt and that you have enough cash to handle vacancies, repairs, and a higher monthly payment.
I see HELOC financing as viable when you need to close quickly and can only buy with cash (non-financeable property). After the purchase and renovation, you can then take out a 30-year fixed-rate loan to pay back the usually higher-rate, higher-risk HELOC.
Hard-Money or Private-Money Loans
These short-term loans are often used for fix-and-flip projects or properties requiring substantial renovation. Approval may depend heavily on the property’s current and projected value. These loans can close quickly but typically carry higher rates, fees, and down-payment requirements. For example, the hard-money loans clients used had an interest rate three to five percentage points above the prime rate and closing costs of approximately 5% of the loan amount. Although the payments were based on a 20-year amortization schedule, the loans matured after only 12 or 18 months, requiring the remaining balance to be repaid or refinanced at that time. Investors should have a clear renovation budget and exit strategy before borrowing.
Non Recourse Loans
You may be able to purchase and finance investment properties through a self-directed IRA. Because the IRA owner generally cannot personally guarantee the debt, the loan must be non-recourse. A non-recourse loan is secured primarily by the property and its income rather than by the IRA owner’s personal assets. If the loan defaults, the lender may take the property and other pledged collateral but generally cannot pursue the IRA owner personally for any remaining balance.
Self-directed IRA transactions are subject to strict tax and prohibited-transaction rules. Financing may also generate unrelated business income tax on debt-financed income. Consult a qualified tax professional and self-directed IRA custodian before proceeding.
Seller Financing
In some transactions, the seller may agree to accept payments over time rather than receiving the entire purchase price at closing.
AITD or Mortgage Wrap
An all-inclusive trust deed, often called an AITD or wraparound mortgage, lets a buyer purchase a property while the seller’s existing loan stays in place. The buyer makes payments under a new note to the seller, usually through a loan servicer, and the seller continues paying the original mortgage. This is not the same as formally assuming the seller’s loan because (in this case) the seller usually remains responsible for that debt, while formally assuming the seller’s loan means the buyer becomes responsible for that debt after closing.
The biggest concern is the due-on-sale clause, which may let the original lender demand full repayment when ownership changes without its consent. Both sides also face risk if payments are late, insurance lapses, or the person responsible for forwarding the money fails to do so. Before using a wrap, have a real estate attorney and title professional review the existing loan documents, payment process, insurance coverage, disclosures, and state-law requirements.
Most sellers won’t sell with a mortgage wrap because they want to get rid of the debt when they sell. It may only make sense to a (distressed) seller when the available alternatives are worse than a mortgage wrap sale.
We have completed a few mortgage wraps, and they are complex and need legal review and an understanding of all the potential pitfalls.
Summary
Every financing method involves trade-offs. Compare the interest rate, monthly payment, closing costs, prepayment penalties, reserve requirements, risk, and long-term cash flow—not simply the down payment. An experienced mortgage professional, tax adviser, and real-estate attorney can help you evaluate the options for your particular investment.
Related insights
New to Real Estate Investing Series — Single-Family or Multifamily?
We’re back this week with our new-to-real-estate-investing series. In the first article in this series, we discussed the first step a new investor needs…
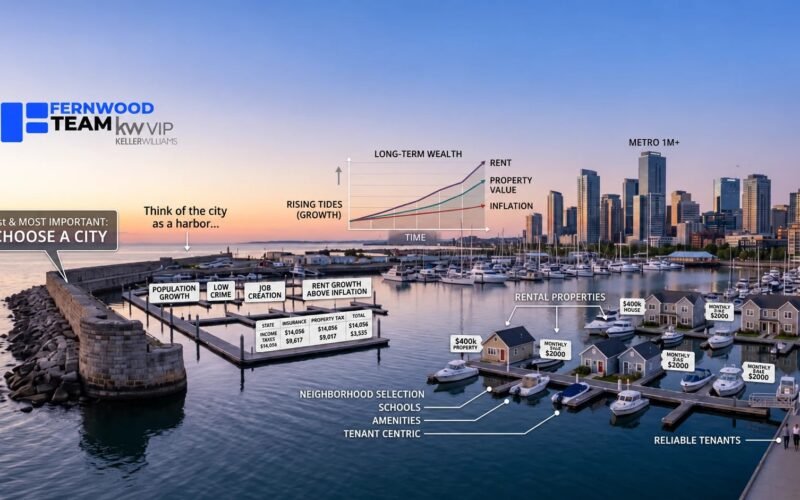
New to Real Estate Investing Series – Where Should I Start?
Most of our clients started with no real estate investing experience and a similar goal: “I want to learn how to build long-term wealth…
The Affordability Fix Nobody Wants to Talk About — and Why It Won’t Reach Our Target Market
Building more homes is the most effective way to improve housing affordability. But in the Las Vegas segment we target, scarce land and high…
Thinking about a Las Vegas rental?
A 30-minute conversation about your goals: whether Las Vegas fits your strategy, what a first property costs, and what the process looks like.
- We learn your goals and make sure we’re the right fit
- You get a clear picture of cash requirements and realistic returns
- You leave with next steps, whether or not you work with us